Landlord insurance · New Jersey
Your rental property needs a different kind of policy.
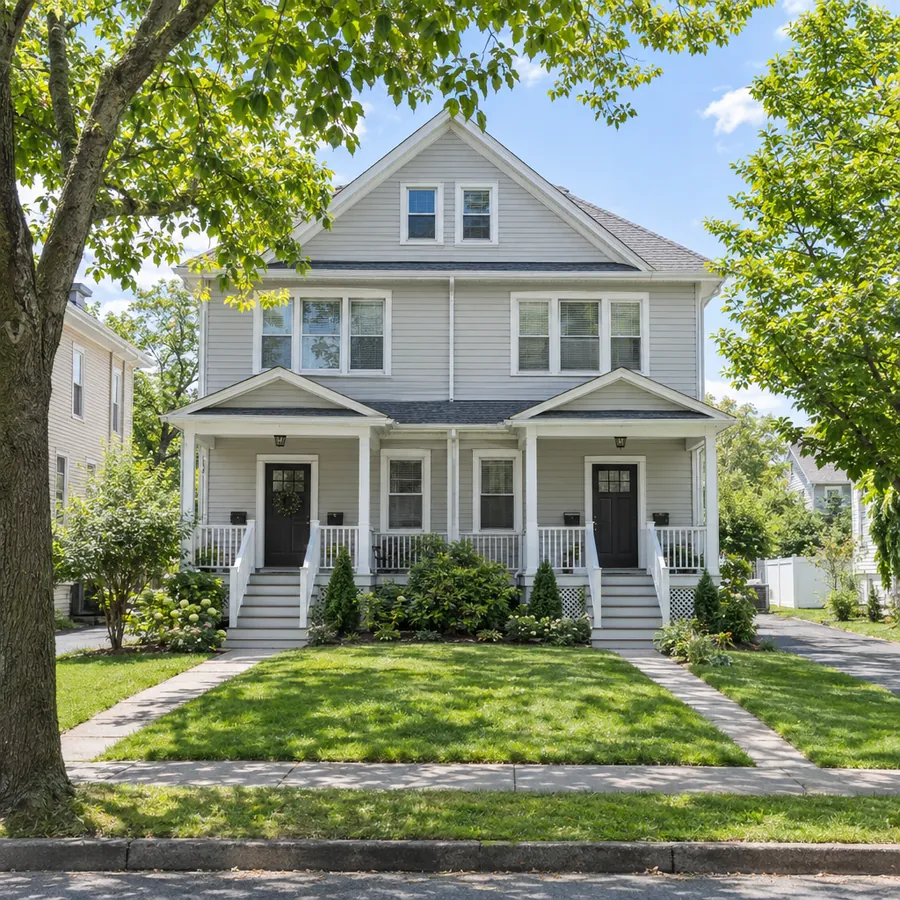
A homeowners policy is built for a home you live in. The day a tenant moves in, the risks change and so should the insurance. Whether you rent out a single condo or a classic NJ 2-4 family house, we match the dwelling policy to how the property is actually used.
 Landlord
What it covers
What a landlord policy can cover
Often called a dwelling fire policy, it protects the building and the income it produces.
Dwelling coverage
The building itself against fire, wind, water damage, vandalism and other covered causes. We help you set a realistic rebuilding limit, not just the market price.
Other structures and your property
Detached garages, sheds and fences, plus items you own that stay with the rental: appliances, lawn equipment, furnishings in a furnished unit.
Premises liability
If a tenant or guest is injured on the property and you are held responsible, for example a fall on a broken step, liability coverage defends and pays up to your limit.
Loss of rents
If a covered loss makes the unit unlivable, the policy can replace the rent you lose while repairs are made, so the mortgage still gets paid.
Vandalism and tenant damage options
Malicious damage and vandalism can be added on many dwelling policies. Wear and tear is never covered, but intentional damage often can be.
Ordinance or law
Older NJ buildings may need upgrades to meet current code after a loss. This coverage pays for the required rebuilding work, not just replacing what was there.
Claims
When a claim hits, we move.
One number to call, one team that follows it to the check.
Get my free quote- 01
Tell us what happened
One call or a short note with photos. We log the details and open the claim with your carrier the same day.
- 02
We file it for you
Estimates, forms and documents go through us. You sign, we submit, and we keep copies of everything.
- 03
We follow it to payment
We stay on the adjuster until the check is right. If something looks off, we push back with you.
New Jersey notes
Landlord realities in New Jersey
NJ’s housing stock and rules shape the policy you need.
2-4 family homes are a NJ staple
Duplexes and multi-family homes are everywhere in North Jersey, and many owners live in one unit while renting the others. The right policy form depends on whether you live there and how many units you rent.
Do not insure a rental as your home
Keeping a homeowners policy on a tenant-occupied property can jeopardize a claim, because the risk is not what the policy was priced for. A proper landlord policy is usually similar in cost and correctly rated.
Vacancy changes coverage
Between tenants, during renovations or while the unit is listed, some coverages shrink or disappear after the property sits empty for a period. Tell us when a unit will be vacant so we keep you covered.
Require renters insurance in your lease
Your policy covers the building and your liability, not the tenant’s belongings or their negligence. Requiring each tenant to carry renters insurance protects both of you, and we can help you word the requirement.
Who it is for
Built for NJ rental owners
From one inherited house to a small portfolio, the logic is the same.
Get my free quote- Owner of a 2-4 family home living in one unit and renting the rest
- Inherited or longtime family property that is now a rental
- A first investment property and its first tenant
- A condo or townhouse rented out after moving to a new home
- A unit sitting vacant between tenants or during a renovation
- Multiple rentals that could be consolidated under one carrier
Questions
Landlord insurance questions we hear every week
Can I keep a homeowners policy on a house I rent out?
It is risky. A homeowners policy is priced and underwritten for an owner-occupied home. If a tenant lives there, a serious claim can be disputed or denied. A landlord dwelling policy is the correct product and often costs about the same.
Does the policy cover damage caused by tenants?
Accidental covered losses, like a kitchen fire, generally are. Intentional or malicious damage and vandalism can often be added as an option. Normal wear and tear is never covered. We will show you exactly where your policy draws those lines.
What happens to my rent if the unit becomes unlivable?
With loss of rents coverage, the policy can reimburse the rental income you lose while a covered loss is repaired. Without it, the mortgage and taxes keep coming while the rent stops.
Should my tenants have their own insurance?
Yes, and we recommend requiring it in the lease. Renters insurance covers the tenant’s belongings and their own liability, so a tenant who causes a fire has their own policy to respond. It also removes the false expectation that your policy covers their things.
My unit will be empty for a few months. Does that matter?
Yes. Most dwelling policies limit or remove certain coverages, especially vandalism and water damage, after a vacancy period. Call us before the unit sits empty and we will keep the coverage honest.